
Ethereum’s faster-exit plan would leave new validators waiting to earn
A dated three-week entry estimate shows how direct deposits and pooled holdings bear the cost of inactive staking capital. Read the full story on CryptoSlateUnderstand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
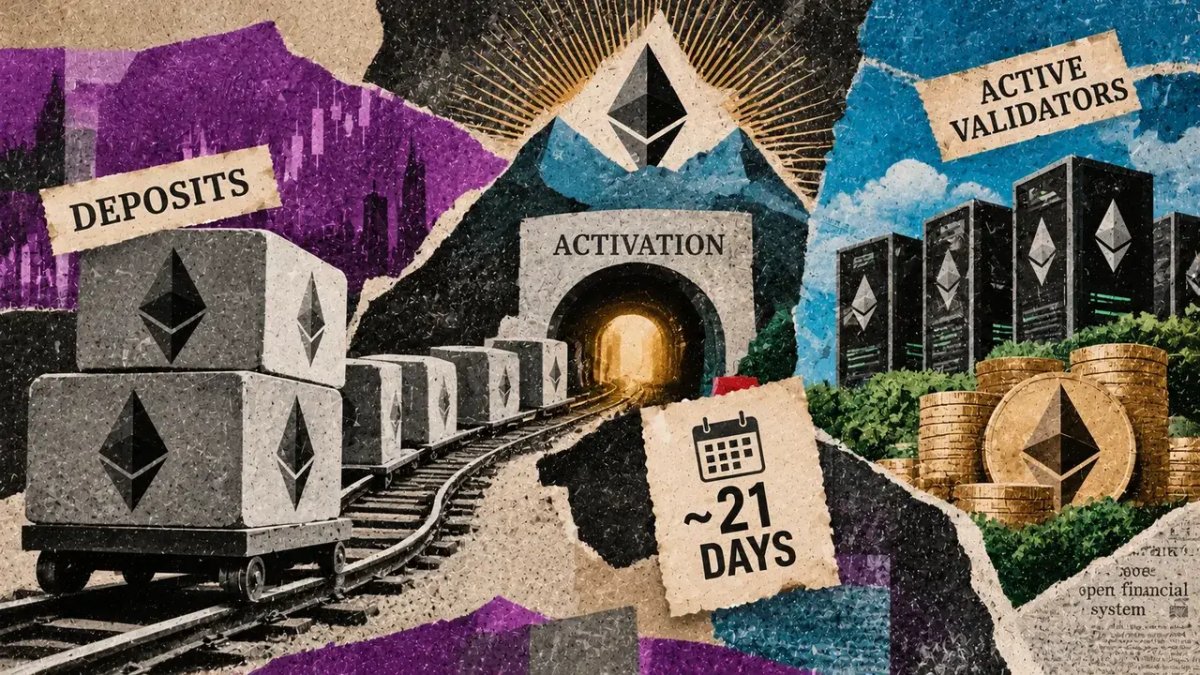
Ethereum staking could get faster exits under EIP-8061, but new validators would still have to wait for capped entry before earning rewards.
Validator Queue displayed 1,282,776 ETH waiting to enter staking and an estimated wait of 22 days, 6 hours when checked on Oct. 15. Its Oct. 14 snapshot, recorded at 21:17 UTC, showed 1,260,628 ETH and an estimated 21 days, 21 hours.
For a direct depositor, the delay postpones native staking income. A liquid staking pool such as Lido can give a new holder exposure to rewards from validators already working. The incoming ETH can still be waiting to activate, leaving more capital sharing those existing earnings.
EIP-8061 would retain the activation ceiling of 256 ETH per epoch. At 6.4 minutes per epoch, that amounts to 57,600 ETH a day when capacity is fully used.
The proposal would remove the fixed cap from exits and make exit capacity scale with active stake. It would also give validator consolidations their own capacity. Exits would remain rate-limited, even with a higher, stake-dependent allowance.
At 36 million ETH of stake, the authors’ worked example produces roughly four times the current capped exit capacity and twice the consolidation capacity.
As of Oct. 15, the EIP remained in Last Call, with a Nov. 1 deadline. Ethereum’s Glamsterdam roadmap listed it as scheduled for inclusion and expected mainnet in the fourth quarter, without a confirmed date. The mainnet consensus configuration had no activation epoch set for Gloas, Glamsterdam’s consensus fork.
A new direct validator deposit earns no native validator rewards while awaiting activation. Active validators earn ETH for their duties, so the economic hurdle is the time before that work begins.
The examples below use constant reward rates and exclude compounding, costs, taxes, penalties and alternative earnings. For 32 ETH inactive over the Oct. 14 snapshot’s estimated 21 days, 21 hours, or 21.875 days, multiply the assumed annual reward rate by 32 and by 21.875 divided by 365. This illustrates what an equally productive active stake could earn during that interval.
| Assumed gross annual reward rate | Illustrative gross rewards over the wait, 32 ETH |
|---|---|
| 2% | 0.038 ETH |
| 3% | 0.058 ETH |
| 4% | 0.077 ETH |
Applying a 10% rewards fee to those illustrative active-stake benchmarks gives about 0.035, 0.052 and 0.069 ETH. Lido’s token integration guide documents that fee rate. A solo validator need not pay it.
Related ReadingWhen a user submits ETH to Lido’s mainnet core pool, the protocol issues stETH, its liquid staking token, and records the holder’s stake through shares. The funds can remain in the buffer or in Ethereum’s pending-deposit queue before earning native rewards.
Under Lido’s share accounting, a holder’s token balance reflects a share of the pool’s accounted ETH. That accounting includes buffered funds, active validator balances, pending deposits and deposits made since the last report. Lido’s separate staking vaults have their own collateral and share accounting; the example below concerns the core pool.
New core-pool shares can participate in subsequent reward distributions before the incoming ETH becomes productive.
If incoming capital stays inactive while existing validators produce the same rewards, those earnings are spread across more capital. Both incoming and incumbent holders share the reduced reward rate. Deposits add backing as well as shares; this is dilution of earnings per unit, not an immediate haircut to principal.