
Binance updates Anthropic mark per second to stop liquidation
Shunyet Jan describes Binance’s perpetual pricing method, while 21Shares’ certificate adds issuer-only recourse, affiliated note terms and costs beyond the 1% fee. Read the full story on CryptoSlateUnderstand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
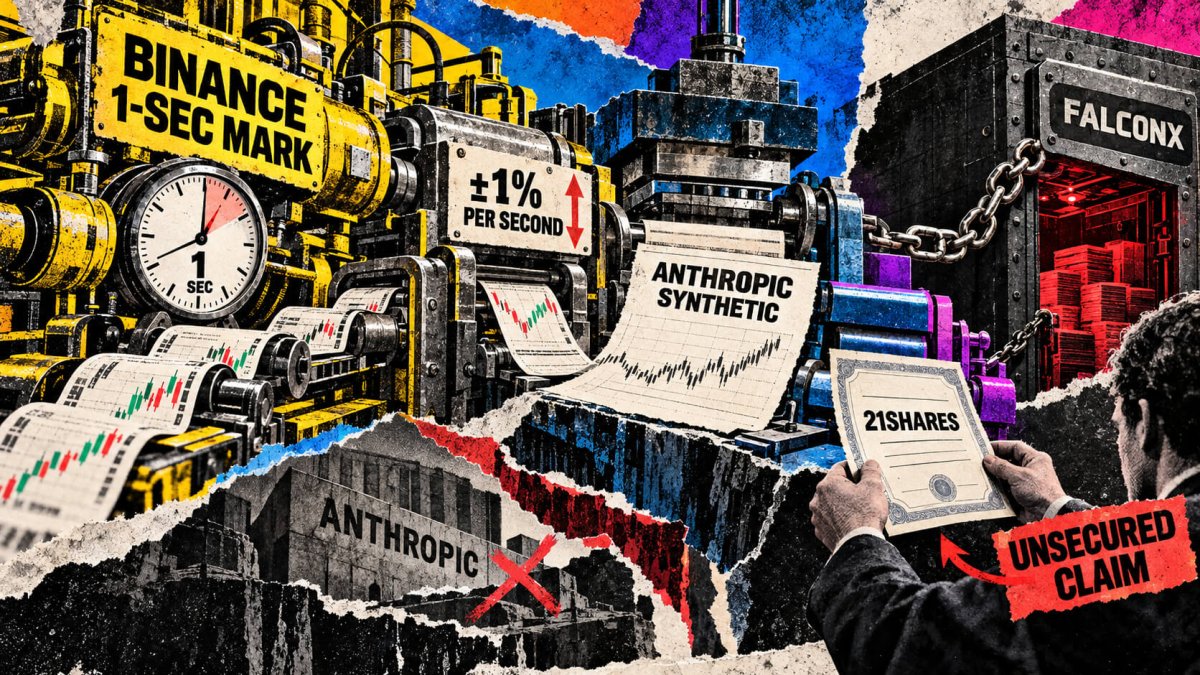
Shunyet Jan, Binance’s Head of Exchange and Trading, explained how Binance prices Anthropic-linked perpetual futures in an Oct. 13 article published by 21Shares.
He describes a mark updated each second from executed trades, with limits on each second’s movement and fallbacks when trading slows.
That explanation accompanies the Oct. 13 contractual issue date of the 21Shares Anthropic Synthetic ETP, an exchange-traded certificate giving synthetic exposure to the private company.
Buyers become unsecured creditors of a Cayman issuer, whose FalconX note counterparty manages the underlying exposure. Their returns depend on that chain’s ability to pay, as well as the direction of Anthropic-linked prices.
The issuer’s legal summary discloses that affiliated contract terms are negotiated within the same corporate group, without an independent director empowered to approve their fairness or an external check that they match an arm’s-length deal. Its advertised 1% annual product fee also sits alongside financing, trading and perpetual-funding costs.
A public listing would force crypto’s synthetic Anthropic valuation to converge with a real stock-market price, testing whether pre-IPO liquidity survives repricing or unwinds once Wall Street sets the benchmark.
This certificate adds a counterparty-failure dependency that can damage returns even if the reference price performs well.
The final terms identify the certificate issuer as 21shares x FalconX Limited, incorporated in the Cayman Islands. They specify one-time long synthetic exposure through an unlisted structured note, with FalconX Sandpiper SPC as the relevant contract counterparty.
The investor holds issuer debt, while the issuer relies on the note counterparty to meet its contractual obligations. According to 21Shares’ explanation, the counterparty manages the economic exposure through perpetual futures traded on Binance and Hyperliquid.
The issue-specific summary classifies the certificates as unsecured and unsubordinated issuer debt, with no guarantee from another entity. Unsubordinated means the obligation is not designated as junior debt.
Investors' recourse is to the issuer alone. If the counterparty defaults or becomes insolvent, the summary warns that the issuer could recover substantially less than the calculated note value, or nothing.
That loss can reach certificate holders regardless of how Anthropic-linked prices have moved.
The certificate-and-note structure assigns derivatives management to the counterparty and the payment obligation to the issuer. It gives the buyer a defined debt claim, but repayment still depends on the issuer’s ability to meet its obligations and on the credit risks embedded in the note.
The legal summary says Jura Pentium Limited owns the issuer within the FalconX Holdings group. The group relationship summary identifies a risk that the issuer and contract counterparty are affiliates under common ownership.
For those contracts, it says entities within the same group agree on fixed prices, slippage, financing costs, and tracking tolerances. These parameters help determine how market exposure translates into economic value for investors.
The document states that no independent director on the issuer’s board has authority to review and approve the fairness of those terms. It also says no external party verifies that they match the terms an unaffiliated counterparty would offer.
The governance limitation does not establish that a particular term is unfair, that prices have been manipulated or that anyone has acted improperly. The issuer says it maintains arrangements to manage potential conflicts, while warning that their effectiveness cannot be assured.
The final terms name NAV Consulting Inc. as calculation agent and administrator. Calculating the certificate’s net asset value is a different task from assessing whether an affiliated note’s negotiated financing or slippage provisions are fair.