
Senate tax bill frees stablecoin spending while Bitcoin stays on IRS forms
The circulated proposal would give eligible dollar-stablecoin purchases no-gain/no-loss treatment without a stated value cap, while ordinary Bitcoin spending retains disposition reporting. The post Senate tax bill frees stablecoin spending while Bitcoin stays on IRS forms appeared first on CryptoSlate.
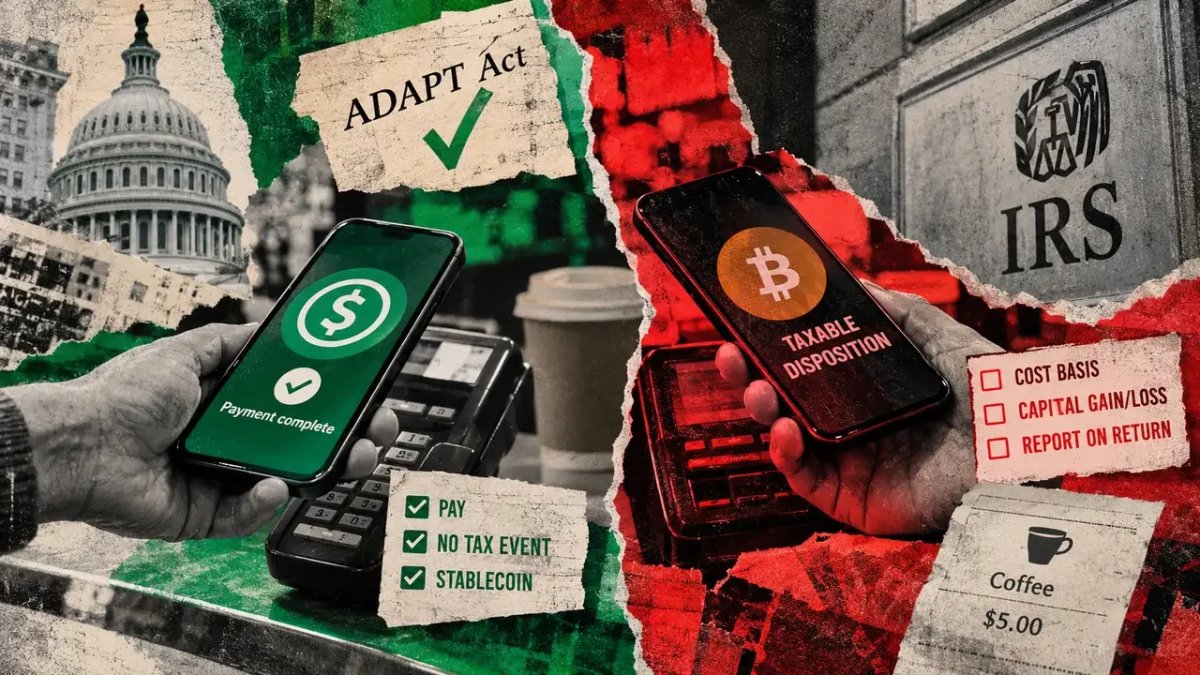
A coffee bought with a qualifying dollar stablecoin would avoid gain-or-loss recognition under the ADAPT Act that Sen. Steve Daines released Sept. 30. The same coffee bought with Bitcoin would still trigger the cost-basis calculation and capital gain or loss reporting that attach to spending digital assets.
Bloomberg Law reported Sept. 25 that Daines had circulated a draft and expected to introduce it the next week. The 56-page text released Sept. 30 carries the title Aligning Digital Assets with Principles of Taxation Act and lists Sens. Cynthia Lummis, Bernie Moreno and Tim Scott of South Carolina as cosponsors.
Under current IRS guidance, paying for goods or services with digital assets in any amount is a disposition. Holders of personal or investment assets must calculate and report capital gain or loss, which depends on the asset's value and cost basis.
A payment can produce a gain, a loss, or a break-even result, and the IRS uses a cup of coffee as its own example. A $5 Bitcoin purchase with an allocated basis of $3 produces a $2 capital gain that belongs on the return.
New section 1034 of the tax code would treat the disposition of covered payment stablecoins to buy products or services as a nonrecognition event. The relief covers gain or loss on the token itself, and sales taxes and other purchase obligations stay in place.
The token must be a qualified US dollar stablecoin, meaning one issued by a permitted payment stablecoin issuer under the GENIUS Act.
A foreign issuer qualifies through OCC registration or a Treasury finding that its home regime is comparable. It must appear in Treasury's most recent report before the payment, and the taxpayer must have acquired it at a price within 3% of $1.00.
Treasury would publish that report at least every three months, listing each qualified stablecoin actively traded within 3% of $1.00 during the 12 months ending the prior month. Users and payment companies would check the latest list when making a purchase.
Traders, brokers, and dealers in qualified dollar stablecoins are excluded, along with taxpayers using a functional currency other than the dollar, and Treasury could extend the trade-or-business exclusion to similar businesses.
Taxpayers must keep records that distinguish eligible payments from other transactions. Covered payments would be exempt from broker information returns under section 6045(i)(1), and brokers could rely on customer certifications and skip verifying the 3% acquisition test for tokens bought elsewhere. The stablecoin provision applies to transactions entered into starting Jan. 1, 2027.
Section 1034 covers stablecoins, so a Bitcoin payment at checkout remains a taxable disposition, while Section 11 adds a narrower rule for fees.