
Native Bitcoin collateral on Aave triggers WBTC pool deficit
Hub suppliers would finance fast exits before permissioned buyers acquire the vaults, with escrow shortfalls reported as deficits. Read the full story on CryptoSlateUnderstand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
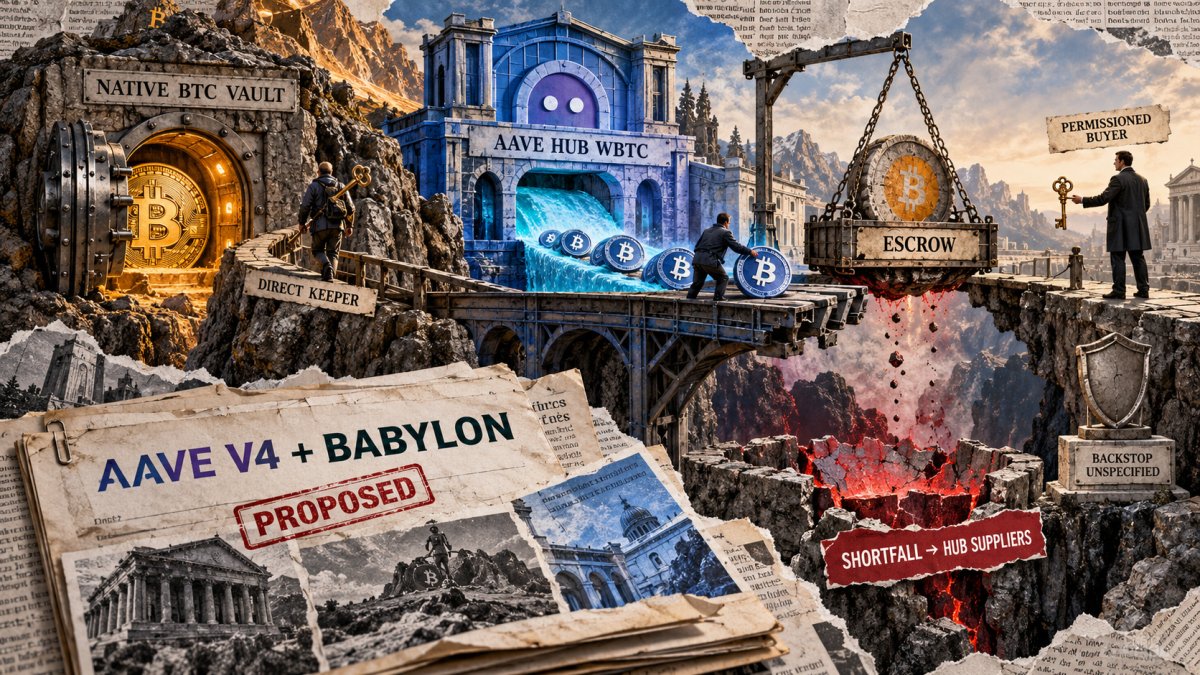
Aave’s proposed native Bitcoin lending market would keep collateral in Bitcoin while borrowing wrapped Bitcoin (WBTC) to pay outside liquidators immediately. Suppliers financing those payouts would face any settlement shortfall without funded protection.
The design in Babylon Labs’ Oct. 14 proposal separates fast liquidation from the slower redemption of Bitcoin collateral. Its open route draws WBTC from Aave’s shared liquidity pool, called a Hub, until a permissioned buyer takes over the vault.
A direct keeper route lets an authorized operator finance repayment and redeem the BTC itself.
The Aave Request for Comment lists feedback, a conditional Snapshot vote, and an eventual on-chain proposal with full risk parameters as subsequent steps.
A borrower would lock BTC in an individual Taproot vault on Bitcoin, and Aave would recognize it through a restricted ERC-20 accounting token that cannot be traded between users. The WBTC used for liquidation settlement is a separate asset.
When a position becomes liquidatable, an outside liquidator would repay the borrower’s debt asset through the integration’s adapter. The seized vault would then be sold to the BTC Vault Swap Spoke, a settlement component that draws WBTC from an Aave Hub and pays the liquidator at an oracle-based price minus a sell discount.
That exchange lets the liquidator leave with a transferable asset in the same transaction. The Swap Spoke would keep the vault in escrow and owe interest on the borrowed WBTC.
An arbitrageur with redemption rights would later acquire the vault by repaying the draw and accrued interest, then claim the BTC on Bitcoin.
Hub liquidity funds the escrow before an arbitrageur buys it. After that purchase, the arbitrageur has committed capital and must wait for Bitcoin redemption, which takes multiple days through the challenge window.
Authorized application vault keepers can repay the borrower’s debt and redeem the seized vault directly to their own Bitcoin key, bypassing the Swap Spoke’s Hub draw. On that route, the keeper finances repayment and the wait for BTC settlement.
| Liquidation route | Immediate settlement | Who finances the wait? |
|---|---|---|
| Open route through the Swap Spoke | Liquidator receives Hub-funded WBTC; vault enters escrow | Hub liquidity until purchase, then the permissioned arbitrageur until Bitcoin settlement |
| Direct application keeper | Keeper repays debt and initiates redemption to its Bitcoin key | The keeper, without the Swap Spoke’s WBTC funding draw |
If the borrower’s entire debt is cleared before that vault’s value is consumed, the liquidator must compensate the borrower for the remainder in WBTC at the liquidation-bonus discount. Even the direct keeper route can require WBTC for this surplus payment.
The Swap Spoke’s WBTC borrowing creates a second debt alongside the borrower’s original loan. Its repayment depends on the escrowed vault attracting an eligible buyer on the specified terms.
If the vault’s current value no longer covers its Hub debt, an arbitrageur can still buy it. The repayment is capped at the vault’s value less a reserved arbitrageur margin, with the unpaid balance reported to the Hub as a deficit in the same transaction.
The reserved margin preserves an incentive to buy the vault and allows the mechanism to complete a purchase while recognizing a loss.
Aave V4’s deficit documentation separates recognition from elimination. Covering a deficit consumes supplied Hub shares belonging to an authorized active Spoke, so someone’s supplied capital must bear the cost of restoring the accounting balance.
TokenLogic’s September coverage framework places deficit exposure with suppliers of the specific Hub asset drawn and tracks the originating Spoke separately.
Under that framework, a shortfall on the proposed WBTC draw would affect suppliers of that Hub asset unless allocated protection absorbed it.
The framework describes DAO deficit offsets as the first loss layer before Umbrella protection where that protection is configured. Its initial recommendations cover three Core lending markets: WETH, USDC and USDT.
WBTC financing falls outside that initial scope, and the Babylon proposal does not specify a funded WBTC backstop.